
Statement of Reasons—Initiation of investigation: Paperboard Cups and Containers (PCC 2026 IN)
Concerning the initiation of the investigations into the alleged dumping and subsidizing of paperboard cups and containers originating in or exported from China.
Decision
Ottawa,
Pursuant to subsection 31(1) of the Special Import Measures Act, the Canada Border Services Agency initiated investigations on August 17, 2026 respecting the alleged injurious dumping and subsidizing of paperboard cups and containers originating in or exported from the People’s Republic of China.
On this page
Summary
[1] On June 22, 2026, the Canada Border Services Agency (CBSA) received a written complaint from Great Pacific Enterprises Limited Partnership, operating as Genpak (Mississauga, ON) (hereinafter, “the complainant”), alleging that imports of certain paperboard cups and containers (hereinafter, “PCC”) originating in or exported from the People’s Republic of China (“China” or “the subject country”), are being injuriously dumped and subsidized. On July 9, 2026, the complainant refiled its complaint in order to correct deficiencies identified by the CBSA.
[2] On July 15, 2026, pursuant to paragraph 32(1)(a) of the Special Import Measures Act (SIMA), the CBSA informed the complainant that the complaint was properly documented. On July 28, 2026, the CBSA informed the Government of China that a properly documented complaint had been filed. At that time, the Government of China was provided with a non-confidential version of the subsidy complaint and was invited for consultations pursuant to Article 13.1 of the Agreement on Subsidies and Countervailing Measures, prior to the initiation of the subsidy investigation. The CBSA did not receive any request for consultations.
[3] The complainant provided evidence to support the allegations that certain PCC from China have been dumped and subsidized, as well as evidence that discloses a reasonable indication that the dumping and subsidizing have caused injury or are threatening to cause injury to the Canadian industry producing like goods.
[4] On August 17, 2026, pursuant to subsection 31(1) of SIMA, the CBSA initiated investigations respecting the dumping and subsidizing of PCC from China.
Interested parties
Complainant
[5] The name and address of the complainant is as follows:
Great Pacific Enterprises Limited Partnership (Genpak)
3185 Pepper Mill Court
Mississauga, Ontario L5L 4X3
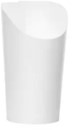
Other producers
[6] The complainant stated that they are the sole domestic producer of PCC.Footnote 1 The Complainant and the CBSA did further supplementary research and identified eight other potential domestic producers of PCC, which were contacted to determine whether they produce like goods. Based on the information available to the CBSA, the Canadian domestic industry is comprised of the complainant, Star Cups and Express Paper Products Inc. (Express Paper).
Trade unions
[7] The complainant stated that its employees are represented by the trade unions Teamsters Local No. 938, United Steelworkers, and the Syndicat des travailleurs et travailleuses des produits manufacturiers et de services.Footnote 2
Exporters
[8] The CBSA identified 225 potential exporters and/or producers of the subject goods from CBSA import documentation and from information submitted in the complaint. All of the potential exporters whose contact information was identified were asked to respond to the CBSA’s Dumping Request for Information (RFI), Subsidy RFI, and Section 20 RFI.
Importers
[9] The CBSA identified 296 potential importers of the subject goods from CBSA import documentation and from information submitted in the complaint. All of the potential importers whose contact information was identified were asked to respond to the CBSA’s Importer RFI.
Government
[10] Upon initiation of the investigations, the Government of China was sent the CBSA’s Government Subsidy RFI and the Government Section 20 RFI.
[11] For the purposes of these investigations, the Government of China refers to all levels of government, i.e., federal, central, provincial/state, regional, municipal, city, township, village, local, legislative, administrative or judicial, singular, collective, elected or appointed. It also includes any person, agency, enterprise, or institution acting for, on behalf of, or under the authority of, or under the authority of any law passed by, the government of that country or that provincial, state or municipal or other local or regional government.
Product information
Definition
[12] For the purpose of these investigations, subject goods are defined as:
Additional product informationFootnote 4
[13] For greater certainty, blanks or flats are the die-cut sections of paperboard that are ready to be formed into a cup or container. A printed roll that has not yet been cut is not a subject good, even if it is imported and destined for die-cutting in Canada. Once flats are cut to the specific shape required for the finished rolled container, they become subject goods; these flats will always be formed into finished paperboard cups and containers and have no other use. For rolled, coated paperboard cups and containers, the blanks are generally the same curved shape, regardless of the rim (see Figure 1 below). Therefore, the subject goods, whether formed (i.e., ready to use) or cut to blanks, are rolled cups and containers made from coated paperboard, which may contain additional layers (such as rippling).
[14] For greater certainty, enhanced clay-coated paperboard containers and their flats are excluded from the definition of subject goods. Certain coated paperboard containers require an enhanced clay coat on the exterior side of the board for end uses where the food item is kept in a frozen state (e.g., ice cream containers). These containers are designed to withstand different use conditions including shipping, storage and longer use than the subject goods. Moreover, they are supplied into vertical processor channels. These requirements include heightened Food and Drug Administration (FDA) compliance requirements, Safe Quality Food (SQF) or equivalent food safety certification, robust product traceability systems, more intensive supplier qualification and approval processes, and comprehensive technical documentation. For these reasons, enhanced clay coat exterior paperboard containers are excluded from the definition of subject goods.
[15] The scope of these investigations does not include paperboard food pails that are formed by folding. These products are manufactured using different processes and equipment, have different shaped blanks, and have different end-uses than the subject goods. This exclusion likewise covers the flats for paperboard food pails, which require specialized equipment that folds the flats into pails, as opposed to rolling them to form the final product.
[16] The scope of these investigations also does not include molded fiber products. Transfer molded products have a rougher texture, lower density, strength and moisture resistance, and looser tolerances for shape than thermoformed molded fiber products, but neither product has the functional characteristics, notably sustained moisture resistance, of coated paperboard products.
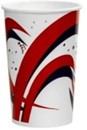
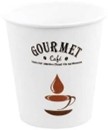
[17] PCC, depicted in Figure 1 below, are the most familiar and common types of coffee cups, soft drink cups, and takeaway soup or other wet food containers on the market.
Figure 1: Illustrations of PCC
[18] PCC are usually constructed from polyethylene (PE) coated paperboard, or a paperboard with a similar coating. The underlying source of the pulp used to produce paperboard (e.g., wood, bamboo, etc.) is not a material distinguishing factor as between subject goods. The definition of the subject goods applies to cups and containers made from paperboard of all varieties, except as specifically excluded.
[19] The coating, PE or other type such as polylactic acid, creates a moisture, grease, and temperature barrier which protects the cups and containers from leaking, softening, or losing structural integrity while holding beverages and food.
[20] The scope of the subject goods includes rolled cups and containers of all sizes, including single walled and double walled cups. Subject goods are usually round and have a flat and raised base; where they are designed to fit a lid, they commonly have a rolled rim. Paperboard cups are generally used for hot and cold drinks and are commonly available in 4-ounce to 32-ounce capacities. Paperboard containers include food containers and “low squat” bowl-style containers ranging in size from 2-ounce to 40-ounce capacities.
[21] PCC may have variations in thickness, coating weight, colour, graphics, barrier properties, and finishing. PCC may also be subject to other processing or treatments, including, but not limited to, hot or after pressing, die-cutting, punching, trimming, padding, perforating, printing, labeling, dying, coloring, coating, laminating, embossing, debossing, repacking, or denesting. Except as excluded, these differentiations do not affect the characteristics or uses of the subject goods.
Production processFootnote 5
[22] PCC are produced through an industry standard multi-step sequential process: printing (if any), die-cutting, and forming and sealing. The process is the same regardless of origin. The equipment used to make PCC cannot be used to make other products.
Printing
[23] The process begins with sourcing and purchasing coated paperboard rolls that meet specific thickness, strength, and performance requirements. Coated paperboard rolls are available in a variety of sizes. The color of the paperboard on such rolls is generally white or off-white, but can also be another color (e.g., brown), and unprinted.
[24] Paperboard rolls are moved from storage and loaded into a printing press using specialized lifting equipment. Artwork and designs are printed directly on the paperboard as it is unspooled using a flexographic printing process capable of printing up to eight colors. Printing always occurs prior to the roll being die-cut.
Die-cutting
[25] Following printing, the paperboard is die-cut into flat blanks with precise dimensions based on the cup or container size. The cutting must align perfectly with the printed design to maintain consistency. Die-cutting may be performed either in-line with the printing operation or off-line as a separate process, depending on the equipment configuration and production requirements. Two die-cut pieces are needed to form the eventual cup or container: the irregular curved piece that forms the main wall of the cup (called the “blank or side wall”), and the disc that forms the base (called the “bottom”).
Forming and sealing
[26] After die-cutting, the flat blanks are transferred to forming machines, which use both mechanical and heat processes. The forming and sealing process is the final step in the manufacturing process, which forms and joins the blank or sidewall and bottom together to form a single, finished product.
[27] First, a mist of water is lightly applied to the pieces as they enter the machine, to make them more workable and less likely to break. Then the blank or sidewall is formed and sealed to itself on a heated mandrel, resulting in an irregular cylindrical shape (essentially a cup without a bottom). Heat activates the PE coating and enables a durable bond to form when the material is pressed together. The base is then formed and joined to the wall structure, again with the application of heat and a mechanical force. Finally, if there is one, the rim at the top of the cup or container is formed with a vertical mechanical stroke. Finished cups and containers are transported to a packaging station where they are checked for quality assurance and packaged for warehousing and distribution.
Classification of imports
[28] The allegedly dumped and subsidized goods are normally imported under the following tariff classification numbers:Footnote 6
- 4823.69.00.10
- 4823.69.00.90
[29] The listing of tariff classification numbers is for convenience of reference only. The tariff classification numbers include non-subject goods. Also, subject goods may fall under tariff classification numbers that are not listed. Refer to the product definition for authoritative details regarding the subject goods.
Like goods and class of goodsFootnote 7
[30] Subsection 2(1) of SIMA defines “like goods” in relation to any other goods as “… (a) goods that are identical in all respects to the other goods, or (b) in the absence of any such goods…, goods the uses and other characteristics of which closely resemble those of the other goods.” In considering the issue of like goods, the Canadian International Trade Tribunal (CITT) typically looks at a number of factors, including the physical characteristics of the goods, their market characteristics, and whether the domestic goods fulfill the same customer needs as the subject goods.
[31] With respect to the definition of like goods, the complainant stated that the subject goods are identical to the like goods produced domestically by the complainant, both in terms of physical characteristics (composition, production methods and appearance) and market characteristics (substitutability, pricing, distribution channels and end uses). As a result of this substitutability, purchasing and contract decisions are made primarily on price.
[32] The complainant states that blanks and flats comprise a single class of goods with fully formed cups and containers. The coated paperboard roll itself can be used for different types of end products, but once the paperboard roll is cut into blanks, it can only be used to form a particular type of end product. The die-cut blanks or flats are essentially the sub-assemblies of the formed cups and containers. The complainant also states that cups and containers comprise a single class of goods due to the minor variations in size and shape.
[33] For the purposes of this analysis, like goods consist of domestically produced PCC described in the product definition.
[34] After considering questions of end-use, physical characteristics, and all other relevant factors, the CBSA is of the opinion that subject goods and like goods constitute only one class of goods.
The Canadian industry
Domestic producers
[35] According to the complainant, they are the only remaining large producer of like goods in Canada.Footnote 8 Based on information provided in the complaint and on its own research, the CBSA sent Standing RFIs to eight potential producers of like goods in Canada to determine whether they produce like goods and to obtain data for the purposes of determining standing. The questionnaires were sent to the potential producers on the same day the CBSA determined that the complaint was properly documented.
[36] Of the eight companies contacted, three replied to the CBSA. Two companies indicated that they do not produce like goods, while Express Paper provided a response to the Standing RFI indicating that they manufacture and sell like goods in Canada. Based on the information available to the CBSA, the Canadian domestic industry is comprised of the complainant, Star Cups and Express Paper.
Estimates of domestic production
[37] The complainant estimates that its own production represents at least 90% of the total domestic production of like goods or even exceeds 90% of all known Canadian production. The complainant provides its own specific production figures but does not estimate specific volumes of production for other Canadian producers.Footnote 9 Express Paper also provided data regarding its own production of like goods in Canada and noted that it supports the complaint.Footnote 10
[38] Based on the information in the complaint and the data provided by Express Paper, the complainant and the supporting producer accounted for the majority of the production of PCC in Canada in 2025 and in the first quarter of 2026.
Standing
[39] Pursuant to subsection 31(2) of SIMA, the following conditions must be met in order for an investigation to be initiated:
- the complaint is supported by domestic producers whose production represents more than 50% of the total production of like goods by those domestic producers who express either support for or opposition to the complaint, and
- the production of the domestic producers who support the complaint represents 25% or more of the total production of like goods by the domestic industry
[40] Based on an analysis of information provided in the complaint, as well as the information gathered by the CBSA, the CBSA is satisfied that the standing requirements of subsection 31(2) of SIMA have been met.
The Canadian market
[41] The complainant, using Statistics Canada import data,Footnote 11 estimated the total volume and value of imports under the tariff classification numbers listed in the complaint from China and all other countries for the period from January 1, 2023, through January 2026.
[42] The CBSA conducted its own independent review of imports of PCC from the CBSA’s Facility Information Retrieval Management (FIRM) database and the CBSA Assessment and Revenue Management (CARM) system using the tariff classification numbers under which the subject goods are imported from China and all other countries. In addition, the CBSA reviewed its Accelerated Commercial Release Operations Support System (ACROSS) data to correct any errors and remove non-subject imports.
[43] Detailed information regarding the sales from domestic production by the complainant as well as the volume of imports of subject goods cannot be divulged for confidentiality reasons. The CBSA, however, has prepared the following table to show the estimated import share of subject goods in Canada:
| Country | 2023 | 2024 | 2025 | Q1 2026 |
|---|---|---|---|---|
| China | 50.6% | 48.8% | 51.8% | 56.2% |
| Other | 49.4% | 51.2% | 48.2% | 43.8% |
| Total | 100.0% | 100.0% | 100.0% | 100.0% |
[44] The CBSA will continue to gather and analyze information on the volume and value of imports during the period of investigation (POI) of April 1, 2025 to March 31, 2026 as part of the preliminary phase of the dumping and subsidy investigations and will refine these estimates.
Evidence of dumping
[45] The complainant alleged that the subject goods from China have been injuriously dumped into Canada. Dumping occurs when the normal value of the goods exceeds the export price to importers in Canada.
[46] Normal values are generally based on the domestic selling price of like goods in the country of export where competitive market conditions exist or as the aggregate of the cost of production of the goods, a reasonable amount for administrative, selling and all other costs, and a reasonable amount for profits.
[47] The complainant made the allegations that the papermaking sector in China may not be operating under competitive market conditions and as such, the domestic market for PCC may not be relied upon for the purpose of determining normal values. Accordingly, the complainant submitted that normal values should be determined under section 20 of SIMA.
[48] The export price of goods sold to importers in Canada is generally the lesser of the exporter’s selling price and the importer’s purchase price, less all costs, charges and expenses resulting from the exportation of the goods.
[49] To ensure that the estimated margins of dumping incorporated a reasonable product mix and were representative of the overall range of subject imports, estimates were conducted for five benchmark products, which were selected as they are the most common in the market: 7 oz hot drink cup; 10 oz hot drink cup; 12 oz hot drink cup; 16 oz cold drink cup; and 8 oz container.
[50] Estimates of normal values and export prices by both the complainant and the CBSA are discussed below.
[51] The complainant calculated margins of dumping for the period of January 1, 2025 to December 31, 2025. The information available made it possible for the CBSA to calculate normal values and export prices for the period of April 1, 2025 to March 31, 2026.
Section 20 allegations
[52] Section 20 is a provision of SIMA that may be applied to determine the normal value of goods in a dumping investigation where certain conditions prevail in the domestic market of the exporting country. In the case of a prescribed country under paragraph 20(1)(a) of SIMA, it is applied where, in the opinion of the CBSA, the government of that country substantially determines domestic prices and there is sufficient reason to believe that the domestic prices are not substantially the same as they would be in a competitive market.Footnote 12
[53] The CBSA initiates dumping investigations on the presumption that section 20 is not applicable to the sector under investigation unless there is information that suggests otherwise.
[54] A section 20 inquiry refers to the process whereby the CBSA collects information from various sources in order to form an opinion as to whether the conditions described under subsection 20(1) of SIMA exist with respect to the sector under investigation. Before initiating an inquiry under section 20, the CBSA must first analyze the information submitted in the complaint and the evidence it has gathered independently to determine if it is sufficient to warrant the initiation of an inquiry.
[55] The complainant alleges that the conditions described in section 20 of SIMA prevail in the papermaking sector in China. That is, the complainant alleges that this industry sector in China does not operate under competitive market conditions and consequently, the domestic prices of PCC established in China would not be reliable for determining normal values. The complainant submitted that the papermaking sector is the relevant sector for this analysis, as it encompasses the production of paperboard as well as of products made of paperboard, namely the subject goods.
[56] In support of its allegations, the complainant provided evidence of state ownership and control of major producers in the papermaking sector; government plans, policies and directives impacting the papermaking sector and associated industries; the role of industry associations as a tool of government control; systemic and sectoral distortions in China, including with respect to land, electricity, labour and capital; government intervention in the cost of production of raw material inputs, notably forestry products, pulp and chemicals; and extensive financial supports and subsidization of producers of PCC. The complainant also provided a pricing analysis comparing Chinese domestic prices of both paperboard, the key input, and PCC with prices from market-economy sources.
[57] The information provided by the complainant suggests a level of government influence in the papermaking sector, including paperboard and PCC. The complainant alleges that the market distortions and cost advantages provided to Chinese producers of forestry products, pulp, paperboard and related inputs translate directly into distortions to the prices of the subject goods in China.
[58] For purposes of the section 20 analysis, the CBSA considers the paperboard tableware sector to be the relevant sector. The CBSA has reviewed the information provided in the complaint and conducted its own research. Based on this information, the CBSA believes that there is reasonable evidence to support an inquiry into the allegations that the measures taken by the Government of China substantially influence prices in the paperboard tableware sector in China, and that the prices are substantially different than they would be in a competitive market.
[59] Consequently, on August 17, 2026, the CBSA included in its investigation a section 20 inquiry in order to determine whether the conditions set forth in paragraph 20(1)(a) of SIMA prevail in the paperboard tableware sector in China.
[60] As part of this section 20 inquiry, the CBSA sent section 20 RFIs to all potential producers and exporters of PCC in China, as well as to the Government of China, requesting detailed information related to the paperboard tableware sector in China.
[61] In cases where conditions of section 20 exist, pursuant to paragraph 20(1)(c), the normal value can be determined based on profitable selling prices or full costs of production and an amount for profit on goods sold domestically in a surrogate country, to which the conditions described in section 20 of SIMA are not applicable.
[62] For the purposes of obtaining information necessary to calculate normal values pursuant to subparagraph 20(1)(c) of SIMA, the CBSA requested information from producers in surrogate countries. As such, the CBSA has selected the United States as the primary potential surrogate country and has sent questionnaires to known producers of PCC in that country.
[63] Additional market-economy countries with significant production or exports of like goods may also be considered as potential surrogates. In the event that the CBSA does not receive sufficient information from producers in the selected surrogate country for the purposes of determining normal values pursuant to section 20, the CBSA may identify other surrogate countries at a later date.
[64] Importers will be requested to provide information on sales of like goods produced in the surrogate countries, in the event that normal values must be determined under paragraph 20(1)(d) of SIMA.
[65] In the event that the CBSA forms an opinion that domestic prices of PCC in China are substantially determined by the government, and there is sufficient reason to believe that the domestic prices are not substantially the same as they would be if they were determined in a competitive market, the normal values of the goods under investigation will be determined, pursuant to paragraph 20(1)(c) of SIMA, where such information is available, on the basis of the domestic selling prices or the aggregate of the cost of production, a reasonable amount for administrative, selling and all other costs, and a reasonable amount for profits of like goods sold by producers in any country designated by the CBSA and adjusted for price comparability; or, pursuant to paragraph 20(1)(d) of SIMA, where such information is available, on the basis of the selling price in Canada of like goods produced and imported from any country designated by the CBSA and adjusted for price comparability.
Normal value
Complainant’s estimates of normal value
Section 15
[66] The complainant stated that in general the sales price for PCC in China was not publicly available at the manufacturer/wholesale level. The complainant was able to obtain retail level pricing, however they explained that there are many problems with using this information to estimate ex-factory normal values as they do not know the retailer’s mark-up, the number of intermediary distributors, or the freight cost.Footnote 13
[67] Nevertheless, the complainant obtained examples of selling prices of PCC in China at the retail level from various e-commerce platforms. To take into account the problems with accepting these prices described above, the complainant applied two levels of deductions to lower the average retail selling price by 27%. A deduction of 8% was applied to account for sales commissions, based on the complainant’s research of the sales commission typically charged by one of the largest online retailers in China. A further deduction of 19% was applied to account for distributor mark-up, based on the average of publicly available 2025 gross margins of three Chinese manufacturers of paper products.Footnote 14
Section 19(b)
[68] The complainant estimated normal values using a constructed cost approach based on the methodology in paragraph 19(b) of SIMA, calculated based on the aggregate of estimates of the cost of production of the subject goods, a reasonable amount for administrative, selling and other costs and a reasonable amount for profits.
[69] As detailed costs of production of PCC producers in China were not available, the complainant estimated the costs of production of PCC in China using:
- FOB port-of-loading price quotes for single- and double-sided poly-coated paperboard obtained from a supplier in China, together with the complainant’s own production data and yield losses, to determine the board cost for each benchmark product (direct material)Footnote 15
- The complainant’s own cost of corrugate, lubricant, ink, sleeves, labels and other direct materialsFootnote 16
- The complainant’s own direct and indirect labour costs adjusted to reflect the difference between manufacturing wages in Canada and ChinaFootnote 17
- The complainant’s factory overhead costsFootnote 18
[70] To estimate a reasonable amount for administrative, selling and other costs, and a reasonable amount for profits for the subject goods from China, the complainant relied on the publicly available financial results of Yibin Paper Industry Co. Ltd., Fuling Technology Co. Ltd. and Hefei Hengxin Life Science & Technology Co. Ltd., three producers of paper products with factories in China. Using this information, the complainant estimated a reasonable amount for administrative, selling and other costs; financial expenses; and profits as a percentage of the costs of production for 2025.Footnote 19
Section 20
[71] The complainant calculated section 20 normal values using the United States as a surrogate country under paragraph 20(1)(c)(ii) of SIMA. The complainant estimated section 20 surrogate normal values in a similar manner as the previously discussed section 19(b) methodology, based on the complainant’s costs of manufacturing adjusted to reflect differences in the US market, including US labour costs, and the amount for administrative, selling and other costs; financial expenses; and profit from the producer Graphic Packaging Holding Company, located in the United States.Footnote 20
CBSA’s estimate of normal value
[72] For the purposes of initiation, the CBSA estimated normal values using a constructed cost approach based on the methodology of paragraph 19(b) of SIMA, calculated based on the aggregate of the estimated cost of production of the goods, a reasonable amount for administrative, selling and other costs, and a reasonable amount for profits. The CBSA reviewed the complainant’s methodology to determine how normal values were estimated and found that the approach was reasonable.
[73] For the purposes of the initiation of the investigation the CBSA has estimated normal values based on the methodology of paragraph 19(b) of SIMA. The CBSA recognizes that there is available information to estimate normal values based on the methodology of section 15 of SIMA, however, all information regarding the domestic selling prices is at the retailer level and not at the producer level. As such, the CBSA finds that the normal values estimated based on the methodology in paragraph 19(b) of SIMA represent the best information available. During the investigations, the CBSA will endeavor to gather additional information regarding domestic prices in China from exporters in order to calculate normal values under section 15 of SIMA.
[74] The CBSA acknowledges that there is reasonable indication that the conditions of section 20 may exist in the paperboard tableware sector in China, however, the CBSA finds the methodology of section 19 to be a reasonable basis for estimating normal values at this stage.
Export price
Complainant’s estimates of export price
[75] The complainant stated that they could not estimate export price based on import data because the tariff classification numbers for PCC cover both subject and non-subject goods. Further, goods can be sold in different units of measure, such as by number of cups or containers or by weight, which can lead to inaccuracies in the data reported.Footnote 21
[76] The complainant instead estimated the export price based on three quotes they received from Chinese manufacturers for sale to Canada.Footnote 22
CBSA’s estimates of export price
[77] In order to estimate the export price for the subject goods imported into Canada, the CBSA used information available through FIRM, CARM and ACROSS. The CBSA was able to obtain sufficient information on importations of Chinese PCC and used this information to estimate export prices.
Estimated margins of dumping
[78] For the purposes of the initiation of the investigation, as previously mentioned, the CBSA has estimated a margin of dumping using normal values based on the methodology of paragraph 19(b) of SIMA.
[79] The CBSA estimated the margin of dumping for the subject goods by comparing the estimated normal values with the estimated export prices for the period of April 1, 2025 to March 31, 2026. Given that normal values and export prices were estimated for five benchmark products, the CBSA took the average margin of dumping across these products. The CBSA estimates that subject goods from China were dumped by 75.8%, expressed as a percentage of the export price.
Evidence of subsidy
[80] In accordance with section 2 of SIMA, a subsidy exists where there is a financial contribution by a government of a country other than Canada that confers a benefit on persons engaged in the production, manufacture, growth, processing, purchase, distribution, transportation, sale, export or import of goods. A subsidy also exists in respect of any form of income or price support within the meaning of Article XVI of the General Agreement on Tariffs and Trade, 1994, being part of Annex 1A to the World Trade Organization (WTO) Agreement that confers a benefit.
[81] Pursuant to subsection 2(1.6) of SIMA, a financial contribution exists where:
- practices of the government involve the direct transfer of funds or liabilities or the contingent transfer of funds or liabilities
- amounts that would otherwise be owing and due to the government are exempted or deducted or amounts that are owing and due to the government are forgiven or not collected
- the government provides goods or services, other than general governmental infrastructure, or purchases goods or
- the government permits or directs a non-governmental body to do anything referred to in any of paragraphs (a) to (c) above where the right or obligation to do the thing is normally vested in the government and the manner in which the non-governmental body does the thing does not differ in a meaningful way from the manner in which the government would do it
[82] A state-owned enterprise (SOE) may be considered to constitute “government” for the purposes of subsection 2(1.6) of SIMA if it possesses, exercises, or is vested with, governmental authority. Without limiting the generality of the foregoing, the CBSA may consider the following factors as indicative of whether the SOE meets this standard: 1) the SOE is granted or vested with authority by statute; 2) the SOE is performing a government function; 3) the SOE is meaningfully controlled by the government; or 4) some combination thereof.
[83] If a subsidy is found to exist, it may be subject to countervailing measures if it is specific. A subsidy is considered to be specific when it is limited, in law or in fact, to a particular enterprise or is a prohibited subsidy. An “enterprise” is defined under SIMA as also including a “group of enterprises, an industry and a group of industries”. Any subsidy which is contingent, in whole or in part, on export performance or on the use of goods that are produced or that originate in the country of export is considered to be a prohibited subsidy and is, therefore, specific according to subsection 2(7.2) of SIMA for the purposes of a subsidy investigation.
[84] In accordance with subsection 2(7.3) of SIMA, notwithstanding that a subsidy is not specific in law, a subsidy may also be considered specific in fact, having regard as to whether:
- there is exclusive use of the subsidy by a limited number of enterprises
- there is predominant use of the subsidy by a particular enterprise
- disproportionately large amounts of the subsidy are granted to a limited number of enterprises and
- the manner in which discretion is exercised by the granting authority indicates that the subsidy is not generally available
[85] For purposes of a subsidy investigation, the CBSA refers to a subsidy that has been found to be specific as an “actionable subsidy”, meaning that it is countervailable.
Subsidy programs in China
[86] In alleging that actionable subsidies were applicable to the subject goods imported from China, the complainant relied on previous CBSA subsidy investigation findings, US Department of Commerce (USDOC) investigations and past countervailing duty findings. The complainant also relied on publications issued by the WTO and Government of China, and general news articles and publications.
[87] In particular, the complainant alleged that the Government of China provides substantial subsidies to its papermaking industry, such as grants, preferential tax treatment, relief from duties and taxes, the provision of land and utilities for less than adequate remuneration, and preferential loans and export credits.Footnote 23
[88] The complainant argued that the CBSA’s numerous recent findings that Chinese paper and other light industrial products were subsidized provided strong evidence that PCC producers also benefited from such subsidies. The complainant relied on previous CBSA findings concerning subsidization in China, including findings concerning Thermoformed Molded Fibre Tableware (TMFT 2025 IN), Mattresses (MAT 2022 IN) etc., as evidence that similar subsidy programs may have benefited PCC producers.Footnote 24
[89] The complainant identified and provided 28 potential subsidy programs that producers and exporters of PCC in China may have benefitted from. The complainant identified, among other programs, export development and performance grants, research and development and other science and technology assistance, industrial and technology transformation assistance, intellectual property related grants, environmental assistance, preferential loan and export credit programs, preferential tax programs, relief from duties and taxes, and the provision of land and utilities for less than adequate remuneration.Footnote 25 The most common support provided by the complainant consists of information from past CBSA findings. The complainant also relied on countervailing findings by the USDOC, China’s notification of active subsidy programs to the WTO in 2023, and other publicly available reports.
[90] The complainant alleged that these subsidy programs are actionable and/or countervailable and that the subsidies are neither negligible nor insignificant. The complainant also claimed that the programs are either used by or are available for use by producers and exporters of PCC in China.
[91] As a result, based on the information available, the CBSA identified 26 potentially actionable subsidy programs that may have benefited Chinese producers/exporters of PCC. Many of these are programs the CBSA has already countervailed in respect of previous subsidy investigations concerning goods from China. These programs have been grouped into the following five categories:
- Grants and grant equivalents
- Preferential tax programs
- Relief from duties and taxes
- Goods/services provided by the government and
- Preferential loans and loan guarantees
[92] The CBSA’s analysis revealed that the alleged subsidy programs constitute potential financial contributions by the Government of China that may have conferred benefits to producers/exporters of PCC. In addition, the programs were further examined and were considered to be potentially specific either in law or in fact within the meaning of subsections 2(7.2) and 2(7.3) of SIMA.
[93] The descriptions of the identified programs to be investigated are found in the subsidy RFI.
[94] If more information becomes available during the investigation process that indicates that some exporters/producers of subject goods may have benefited from any other programs during the POI, the CBSA will request complete information from the Government of China and exporters/producers of subject goods to pursue the investigation of these programs.
CBSA's conclusion
[95] Sufficient evidence is available to support the allegations that PCC originating in or exported from China have been subsidized. In investigating these programs, the CBSA has requested information from the Government of China, exporters and producers to determine whether exporters/producers of subject goods received benefits under these programs and whether these programs, or any other programs, are actionable subsidies and, therefore, countervailable under SIMA.
Estimated amount of subsidy
[96] The complainant was unable to estimate the amounts of subsidy on a program basis for the subject goods imported from China. Instead, the complainant estimated the amount of subsidy as being equal to the difference between the estimated cost of production and the export price for PCC sold into Canada.Footnote 26
[97] It is the CBSA’s understanding that subsidies have the effect of lowering the full cost of the goods, including the cost of production and the amount for selling, administrative and all other costs, which allows exporters to pass-through the subsidy benefits in reducing the selling price of those goods to Canada. Therefore, the CBSA is satisfied that the exporter’s ability to sell subject goods to Canada at prices substantially below their estimated full costs supports the complainant’s allegations that subsidies are being conferred on the exported goods.
[98] The CBSA estimated the amount of subsidy conferred to exporters of the subject goods from China by comparing the estimated full costs of the subject goods with their estimated export prices, using the costing and export price methodologies explained in the evidence of dumping section.
[99] The CBSA’s analysis of the information indicates that subject goods imported into Canada during the period of April 1, 2025 to March 31, 2026 were subsidized and that the estimated amount of subsidy is 49.6% of the export price.
Evidence of injury
[100] The complainant alleges that the subject goods have been dumped and subsidized and that such dumping and subsidizing have caused and are threatening to cause material injury to the PCC industry in Canada.
[101] SIMA refers to material injury caused to the domestic producers of like goods in Canada. The CBSA has concluded that PCC produced by the domestic industry are like goods to the subject goods from China.
[102] Given concerns with respect to the confidentiality of the information of the domestic producer, the CBSA is limited in its ability to discuss certain information contained in the complaint.
[103] In support of their allegations, the complainant provided evidence of:
- Increased import volumes of subject goodsFootnote 27
- Price undercuttingFootnote 28
- Price depressionFootnote 29
- Price suppressionFootnote 30
- Lost sales and a decline in revenuesFootnote 31
- Decline in market shareFootnote 32
- Decline in production levels and capacity utilizationFootnote 33
- Increase in inventory levelsFootnote 34
- Decline in profitabilityFootnote 35
- Reduction in employmentFootnote 36 and
- Adverse impacts on capital investmentsFootnote 37
Increased import volumes of subject goods
[104] The complainant alleges that imports of subject goods have increased in absolute terms since 2023. To support their allegation on an absolute basis, the complainant provided estimates of PCC imports under tariff classification numbers 4823.69.00.10 and 4823.69.00.90 from 2023 to the first quarter of 2026, based on import data obtained from Statistics Canada.Footnote 38
| 2023 | 2024 | 2025 | 2023-2025 % change |
Q1 2025 | Q1 2026 | Q1 2025-Q1 2026 % change |
|
|---|---|---|---|---|---|---|---|
| Volumes (kg) | 39,155,077 | 40,082,664 | 44,289,874 | 13% | 8,331,182 | 10,582,249 | 27% |
| Values ($) | 146,877,777 | 146,527,354 | 149,872,975 | 2% | 30,470,978 | 32,754,008 | 7% |
| AUVs ($/kg) | $3.75 | $3.66 | $3.38 | -10% | $3.66 | $3.10 | -15% |
[105] Based on the import data above, the volume of imports of subject goods have increased in absolute terms, on a volume (kg) basis, by 13% between 2023 and 2025. The complainant further flagged the significant import growth of 27% when comparing subject imports from the first quarter of 2025 to the first quarter of 2026. The complainant also highlighted that most of the increase occurred between the period of 2024 to 2025, suggesting that the pace of Chinese imports is accelerating.Footnote 40
[106] In terms of relative increase, the rise in the volume of subject goods is even more distinct relative to the production and consumption of like goods. While subject import volumes have risen, the volumes of both domestically produced and sold like goods continued to decline.Footnote 41
[107] Based on the CBSA’s import statistics for PCC, imports of subject goods have not increased in absolute terms since 2023. As shown in the following table, estimated imports of PCC from China fell by 27% between 2023 and 2025, and by 8% between 2024 and 2025.
| Country | 2023 | 2024 | 2025 | 2023-2025 % change |
2024-2025 % change |
Q1 2026 |
|---|---|---|---|---|---|---|
| China | 58,820,928 | 46,254,066 | 42,777,149 | -27% | -8% | 9,550,103 |
| Other countries | 57,517,587 | 48,539,637 | 39,733,941 | -31% | -18% | 7,452,953 |
| China's share of total PCC import volume | 51% | 49% | 52% | 56% |
| Country | 2023 | 2024 | 2025 | 2023-2025 % change |
2024-2025 % change |
Q1 2026 |
|---|---|---|---|---|---|---|
| China | $144,594,630 | $134,094,332 | $83,850,359 | -42% | -37% | $18,644,358 |
| Other countries | $294,337,897 | $258,126,399 | $189,999,981 | -35% | -26% | $40,952,628 |
| Country | 2023 | 2024 | 2025 | 2023-2025 % change |
2024-2025 % change |
Q1 2026 |
|---|---|---|---|---|---|---|
| China | $2.46 | $2.90 | $1.96 | -20% | -32% | $1.95 |
| Other countries | $5.12 | $5.32 | $4.78 | -7% | -10% | $5.49 |
[108] While the absolute import volume from China has not increased since 2023, China’s share of total PCC imports has been increasing since 2024. As shown above, China’s share of PCC imports grew 3% in 2025 and a further 4% in the first quarter of 2026, showing China represents 56% of the total estimated imports of PCC.
[109] In combining the CBSA’s import data along with the complainant’s and Express Paper’s production and sales figures, the data showed a similar trend when comparing subject imports in relation to the domestic production and sales of like goods in Canada. Imports of subject goods relative to domestic production and sales of like goods by the Canadian industry increased between 2023 and 2025.
[110] Based on the information and analysis conducted above, the CBSA finds the complainant’s claim of increased import volumes relative to the production or consumption of like goods to be sufficiently supported and reasonably linked to the allegedly dumped and subsidized goods.
Price undercutting
[111] The complainant argues that subject imports have undercut the pricing of domestically produced like goods, resulting in material losses of sales volume and revenue across key customer accounts. They claim that the systematic undercutting has eroded their ability to compete on price in the Canadian market and has forced them to choose between significantly reducing prices or losing volume.Footnote 42
[112] The complainant explains that it is not reasonably possible to present evidence of price undercutting on an aggregate basis using the data from Statistics Canada. This is due to the fact that the Statistics Canada data includes a wide variety of both subject and non-subject goods, as well as numerous different product models whose unit price would vary significantly. However, based on experience, the complainant states that subject imports routinely enter the Canadian market at a price of 30% to 50% below the price of like goods.Footnote 43
[113] To substantiate its claims of undercutting, the complainant provides its own account-specific evidence relating to some of its key customers. The complainant argues that this evidence demonstrates patterns of major customers either shifting their sourcing directly to Chinese suppliers or leveraging Chinese import pricing to extract significant concessions from Genpak, resulting in material losses in sales volume and revenue.Footnote 44
[114] Based on the above, the CBSA finds the claim of price undercutting to be sufficiently supported and reasonably linked to the allegedly dumped and subsidized goods.
Price depression
[115] The complainant asserts that the sustained presence of the subject goods in the Canadian market have depressed the prices of like goods being sold in Canada. They note that their Canadian customers routinely ask them to match price quotes obtained from Chinese exporters, prices which are “structurally unachievable under Canadian cost conditions”. To support its claim, the complainant also provided data showing that their average unit pricing for 8 out of 10 of their largest selling product models in 2025 declined or remained flat over the 2023-2025 period.Footnote 45
[116] The complainant also included a table showing average unit pricing for the same top ten models during the 2023-2025 period, but where the prices had been adjusted for inflation. The figures showed the same trends and calculated an average rate of depression over the period.Footnote 46
[117] Based on its own import data, the complainant notes that the decline in its own pricing coincides with the increase in subject imports along with a decline in the average aggregate price of subject imports. The complainant also noted that over the same period, non-subject import prices remained flat or increased as shown below.Footnote 47
| Tariff number | 2023 | 2024 | 2025 | 2023-2025 % change |
|---|---|---|---|---|
| 4823.69.00.10 | $3.92 | $3.70 | $3.39 | -13.6% |
| 4823.69.00.90 | $3.63 | $3.63 | $3.38 | -6.9% |
| Tariff number | 2023 | 2024 | 2025 | 2023-2025 % change |
|---|---|---|---|---|
| 4823.69.00.10 | $6.35 | $6.83 | $6.34 | -0.2% |
| 4823.69.00.90 | $6.41 | $6.61 | $6.56 | 2.4% |
[118] As shown in the following table, the CBSA’s import data shows pricing trends generally similar to those presented by the complainant. With respect to the tariff number 4823.69.00.10, unlike the complainant’s data, CBSA data shows the average price for subject goods rising in 2024 before declining by 30.9% in 2025. CBSA data for that tariff number also shows that average pricing for subject goods fell 7.2% in the first quarter of 2026 as compared to the previous year. With respect to subject goods imported under 4823.69.00.90, CBSA data shows average prices falling continuously over the 2023-2025 period, not just in 2025 as presented in the complaint. Of particular note, average pricing under that tariff number dropped 32.1% year-over-year in 2025, and despite increasing in the first quarter of 2026, remained below pricing in 2023 and 2024.
| Tariff number | 2023 | 2024 | 2025 | Q1 2026 | 2023-2025 % change |
2024-2025 % change |
2025-Q1 2026 % change |
|---|---|---|---|---|---|---|---|
| 4823.69.00.10 | $1.90 | $2.77 | $1.91 | $1.78 | 0.8% | -30.9% | -7.2% |
| 4823.69.00.90 | $3.19 | $3.01 | $2.04 | $2.42 | -35.9% | -32.1% | 18.5% |
| Tariff number | 2023 | 2024 | 2025 | Q1 2026 | 2023-2025 % change |
2024-2025 % change |
2025-Q1 2026 % change |
|---|---|---|---|---|---|---|---|
| 4823.69.00.10 | $4.98 | $5.02 | $5.60 | $5.37 | 12.4% | 11.6% | -4.2% |
| 4823.69.00.90 | $5.42 | $6.04 | $3.06 | $6.02 | -43.5% | -49.3% | 96.7% |
[119] Based on the information and analysis above, the CBSA finds the claim of price depression to be sufficiently supported and reasonably linked to the allegedly dumped and subsidized goods.
Price suppression
[120] The complainant argues that it experienced price suppression and supports the allegation by demonstrating that the costs of production rose for the 2023-2025 period, a period during which they were unable to meaningfully raise the price of like goods. The complainant notes that customers have explicitly rejected its attempts to increase prices and cited the availability of low-priced subject goods for their reasoning. The complainant supported its argument by providing a table detailing its cost and sales data over the period. The complainant also provided data showing that the adverse impacts of price suppression were particularly evident when focusing on material and labour costs.Footnote 49
[121] Based on the above, the CBSA finds the claim of price suppression to be sufficiently supported and reasonably linked to the allegedly dumped and subsidized goods.
Lost sales and a decline in revenues
[122] The complainant contends that competition with the subject goods has caused a decline in its domestic sales of like goods, both in terms of volume and revenue, in each consecutive year during the 2023 to first quarter 2026 period. To support this contention, they provide overall sales data during that period as well as account specific data showing the impact on annual sales volumes to their top ten Canadian customers. In addition to showing the overall impact on its top ten customers, the complainant also provides substantial details with supporting evidence demonstrating the impact competition with the subject goods have had on 14 customer-specific accounts.Footnote 50
[123] The CBSA finds that the overall domestic sales data and account specific evidence of lost sales, when taken together with the relative increase in subject imports and lower average unit values of the imports discussed earlier, is sufficient to establish a reasonable indication that the domestic industry lost sales as a result of the presence of and competition with subject goods in the Canadian market.
Decline in market share
[124] The complaint alleges that competition with the subject goods has caused its market share to decline over the 2023-2025 period and supports its allegation by comparing their sales data with the import data. They also highlight the evidence of head-to-head competition in their examples of lost sales to specific customers as further supporting this allegation.Footnote 51
[125] According to the CBSA’s estimation of the total apparent Canadian market for subject and like goods, Canadian producers do not appear to have lost market share to subject imports. The CBSA found that the total market shrank over the 2023–2025 period, and the domestic producers’ market share stayed flat until it rose in the first quarter of 2026. That CBSA’s estimated market data also suggests that the subject goods market share gain in 2025 came at the expense of goods imported from other countries. However, the subject goods significantly increased their market share in the first quarter of 2026, while the domestic producers’ share only increased slightly.
[126] Based on the information and analysis above, the CBSA agrees that subject goods gained market share over the period. However, the CBSA does not find the Canadian producers’ market share declined over the period. As such, the complainant’s claim of declining market share is not sufficiently supported and reasonably linked to the allegedly dumped and subsidized goods.
Decline in production levels and capacity utilization
[127] The complainant submits that competition with the subject goods has caused their production levels and capacity utilization levels to fall over the 2023-2025 period. They state that they have been unable to replace lost sales volumes with new business due to the availability of low-priced Chinese imports in the Canadian market, which has led to lower levels of production. In addition, they note that the underutilization of capacity has resulted in the reduced absorption of fixed costs, leading to reduced margins and profitability. To support their allegation, the complainant provides capacity and production data for each of its Canadian facilities over the period of 2023 though to the first quarter of 2026.Footnote 52
[128] Based on the above, the CBSA finds the claim of lower production volumes and increasing capacity underutilization to be sufficiently supported and reasonably linked to the allegedly dumped and subsidized goods.
Increase in inventory levels
[129] The complainant submits that inventory levels have risen as a result of the declining sales due to the competition with the allegedly dumped subject goods. This includes unprinted products, generic printed products, as well as customer-specific printed products. The complainant also noted the impact of the inventory level increases are magnified when considering how production has declined over the same period. To support its claim, the complainant provided inventory value and volume data.Footnote 53
[130] Based on the above, the CBSA finds the claim of increasing inventory levels to be sufficiently supported and reasonably linked to the allegedly dumped and subsidized goods.
Decline in profitability
[131] The complainant argues that its profitability has deteriorated materially between 2023 and the first quarter of 2026 as a result of both price suppression and lost sales volumes directly attributable to the severe competitive pressure created by the imports of allegedly dumped subject goods. The complaint also states that the decline in financial performance threatens the company’s long-term viability and ability to compete in the Canadian market. The complainant supported its arguments by providing its own financial data and showing trends with respect to its profitability on like goods.Footnote 54
[132] Based on the above, the CBSA finds the claim of a decline in profitability to be sufficiently supported and reasonably linked to the allegedly dumped and subsidized goods.
Reduction in employment
[133] The complainant claims that it has also experienced a material impact on employment as a result of competing with the subject goods. Due to deteriorating financial performance caused by the declines in sales, the complainant was driven to reduce its workforce in 2025. They note that the timing of the employment reductions aligns with the periods in which subject import volumes increased the most, based on their import statistics. They argue that the workforce reductions and underutilization of labour represent material injury to the Canadian industry. To support this claim, the complainant provided tables detailing like goods related employment figures during the period of 2023 through to the first quarter of 2026.Footnote 55
[134] Based on the information submitted by the complainant, the CBSA finds the claim of a reduction in employment to be sufficiently supported and reasonably linked to the allegedly dumped and subsidized goods.
Adverse impacts on capital investments
[135] The complainant states that declines in its sales and profitability, a result of competition with the subject goods, have materially constrained capital investments, which negatively impact actual and potential growth. The complainant notes that the industry is capital-intensive and technology-driven, and that domestic producers must continuously invest in new equipment and process improvements to remain competitive. The complainant supports its position by providing details regarding its investment plans over the period covered by this complaint.Footnote 56
[136] In reviewing the confidential information and supporting documentation provided in the complaint,Footnote 57 the CBSA was unable to make a direct link between the evidence provided and the complainant’s allegation. As a result, the CBSA does not find the claim of adverse impacts on its capital investments to be sufficiently supported and reasonably linked to the allegedly dumped and subsidized goods.
CBSA's injury conclusion
[137] Overall, based on the evidence provided in the complaint, and supplementary data available to the CBSA through its own research and customs documentation, the CBSA finds that the evidence discloses a reasonable indication that the dumping and subsidizing of the subject goods from China, have caused injury to the PCC industry in Canada in the form of:
- increased import volumes of subject goods
- price undercutting
- price depression
- price suppression
- lost sales and a decline in revenues
- a decline in production levels and capacity utilization
- increased inventory levels
- a decline in profitability and
- reductions in employment
Threat of injury
[138] The complainant alleged that the dumped and subsidized goods threaten to cause further material injury to the domestic industry and provided evidence for each of the following factors to support its allegation:
- An anticipated significant increase in forming capacity in Canada by Genpak competitors using subject blanks or flats imported from ChinaFootnote 58
- Structural overcapacity and increasing excess capacity in ChinaFootnote 59
- The rate of increase in dumped and subsidized subject imports and the likelihood of increasing import volumesFootnote 60
- Imports of subject goods are priced sufficiently low enough to depress Canadian prices and stimulate increased demand for subject importsFootnote 61 and
- Trade remedy measures by other countries on similar paper products from ChinaFootnote 62
[139] In light of the CBSA’s finding that there is a reasonable indication that the dumping and subsidizing of the subject goods has caused injury, the CBSA will exercise administrative efficiency and not address whether there is a reasonable indication that the dumping and subsidizing of the subject goods is threatening to cause injury.
Scope of the investigations
[140] The CBSA is conducting investigations to determine whether the subject goods have been dumped and/or subsidized.
[141] The CBSA has requested information from all potential exporters and importers whose contact information was identified to determine whether or not subject goods imported into Canada during the POI of April 1, 2025 to March 31, 2026 were dumped and/or subsidized. The information requested will be used to determine the normal values, export prices and margins of dumping, if any. The CBSA also requested information from the Government of China with respect to the possibility that the conditions of section 20 of SIMA exist in the paperboard tableware sector in China.
[142] The CBSA has also requested information from the Government of China and all potential producers/exporters to determine whether or not subject goods imported into Canada during the POI of April 1, 2025 to March 31, 2026 were subsidized. The information requested will be used to determine the amounts of subsidy, if any.
[143] All parties have been clearly advised of the CBSA’s information requirements and the time frames for providing their responses.
Future action
[144] The CITT will conduct a preliminary inquiry to determine whether the evidence discloses a reasonable indication that the alleged dumping and subsidizing of the goods has caused or is threatening to cause injury to the Canadian industry. The CITT must make its decision on or before the 60th day after the date of the initiation of the investigations. If the CITT concludes that the evidence does not disclose a reasonable indication of injury to the Canadian industry, the investigations will be terminated.
[145] If the CITT finds that the evidence discloses a reasonable indication of injury to the Canadian industry and the CBSA’s preliminary investigation reveals that the goods have been dumped and/or subsidized, the CBSA will make a preliminary determination of dumping and/or subsidizing within 90 days after the date of the initiation of the investigations, by November 16, 2026. Where circumstances warrant, this period may be extended to 135 days from the date of the initiation of the investigations.
[146] Under section 35 of SIMA, if, at any time before making a preliminary determination, the CBSA is satisfied that the volume of goods of a country is negligible, the investigations will be terminated with respect to goods of that country.
[147] Imports of subject goods released by the CBSA on and after the date of a preliminary determination of dumping and/or subsidizing, other than goods of the same description as goods in respect of which a determination was made that the margin of dumping of, or the amount of subsidy on, the goods is insignificant, may be subject to provisional duty in an amount not greater than the estimated margin of dumping and/or the estimated amount of subsidy on the imported goods.
[148] Should the CBSA make a preliminary determination of dumping and/or subsidizing, the investigations will be continued for the purpose of making a final decision within 90 days after the date of the preliminary determinations.
[149] After the preliminary determinations, if, in respect of goods of a particular exporter, the CBSA’s investigations reveal that imports of the subject goods from that exporter have not been dumped or subsidized, or that the margin of dumping or amount of subsidy is insignificant, the investigation(s) will be terminated in respect of those goods.
[150] If final determinations of dumping and/or subsidizing are made, the CITT will continue its inquiry and hold public hearings into the question of material injury to the Canadian industry. The CITT is required to make a finding with respect to the goods to which the final determinations of dumping and/or subsidizing apply, not later than 120 days after the CBSA’s preliminary determinations.
[151] In the event of an injury finding by the CITT, imports of subject goods released by the CBSA after that date will be subject to anti-dumping duty equal to the applicable margin of dumping and countervailing duty equal to the amount of subsidy on the imported goods. Should both anti-dumping and countervailing duties be applicable to subject goods, the amount of any anti-dumping duty may be reduced by the amount that is attributable to an export subsidy.
Retroactive duty on massive importations
[152] When the CITT conducts an inquiry concerning injury to the Canadian industry, it may consider if dumped and/or subsidized goods that were imported close to or after the initiation of the investigations constitute massive importations over a relatively short period of time and have caused injury to the Canadian industry.
[153] Should the CITT issue such a finding, anti-dumping and countervailing duties may be imposed retroactively on subject goods imported into Canada and released by the CBSA during the period of 90 days preceding the day of the CBSA making preliminary determinations of dumping and/or subsidizing.
[154] In respect of importations of subsidized goods that have caused injury, however, this provision is only applicable where the CBSA has determined that the whole or any part of the subsidy on the goods is a prohibited subsidy, as explained in the previous “Evidence of subsidy” section. In such a case, the amount of countervailing duty applied on a retroactive basis will be equal to the amount of subsidy on the goods that is a prohibited subsidy.
Undertakings
[155] After a preliminary determination of dumping by the CBSA, other than a preliminary determination in which a determination was made that the margin of dumping of the goods is insignificant, an exporter may submit a written undertaking to revise selling prices to Canada so that the margin of dumping or the injury caused by the dumping is eliminated.
[156] Similarly, after the CBSA has rendered a preliminary determination of subsidizing, a foreign government may submit a written undertaking to eliminate the subsidy on the goods exported or to eliminate the injurious effect of the subsidy, by limiting the amount of the subsidy or the quantity of goods exported to Canada. Alternatively, exporters with the written consent of their government may undertake to revise their selling prices so that the amount of the subsidy or the injurious effect of the subsidy is eliminated.
[157] An acceptable undertaking must account for all or substantially all of the exports to Canada of the dumped or subsidized goods. Interested parties may provide comments regarding the acceptability of undertakings within nine days of the receipt of an undertaking by the CBSA. The CBSA will maintain a list of parties who wish to be notified should an undertaking proposal be received. Those who are interested in being notified should provide their name, telephone number, mailing address and email address to one of the officers identified in the Contact us section of this document.
[158] If undertakings were to be accepted, the investigations and the collection of provisional duties would be suspended. Notwithstanding the acceptance of an undertaking, an exporter may request that the CBSA’s investigations be completed and that the CITT complete its injury inquiry.
Publication
[159] Notice of the initiation of these investigations is being published in the Canada Gazette pursuant to subparagraph 34(1)(a)(ii) of SIMA.
Contact us
[160] Interested parties are invited to file written submissions presenting facts, arguments, and evidence that they feel are relevant to the alleged dumping. Written submissions must be filed through CBSA’s ACE web application.
[161] To be given consideration in these investigations, all information should be received by the CBSA by December 23, 2026, at noon.
[162] Any information submitted to the CBSA by interested parties concerning these investigations is considered to be public information unless clearly marked “confidential”. Where the submission by an interested party is confidential, a non-confidential version of the submission must be provided at the same time. This non-confidential version will be made available to other interested parties upon request.
[163] Confidential information submitted to the CBSA will be disclosed on written request to independent counsel for parties to these proceedings, subject to conditions to protect the confidentiality of the information. Confidential information may also be released to the CITT, any court in Canada, or a WTO or Canada-United States-Mexico Agreement (CUSMA) dispute settlement panel. Additional information respecting the CBSA’s policy on the disclosure of information under SIMA may be obtained by contacting the CBSA at the email address identified below.
[164] The schedule of the investigations and a complete listing of all exhibits and information are available through the CBSA’s Dumping and subsidy investigations. The exhibit listing will be updated as new exhibits and information are made available.
[165] For further information, please contact the CBSA at:
Email: trade_remedies_registry-registre_recours_commerciaux@cbsa-asfc.gc.ca
Sean Borg
a/Executive Director
Trade Remedies Investigations Division
Page details
- Date modified: